Retail data,commerce,and AI agents.The three forces reshaping online advertising in 2026 are all converging on one place: the CTV screen.If you operate your own OTT inventory,you may be sitting in the best seat in the house right now.Look closely at this y...
In 2026, Advertising Is Converging on the TV Screen - 5 Opportunities OTT Operators Should Be Watching
CK 3398 Created at Updated at
3,51900
Retail data, commerce, and AI agents. The three forces reshaping online advertising in 2026 are all converging on one place: the CTV screen. If you operate your own OTT inventory, you may be sitting in the best seat in the house right now.
Look closely at this year's ad market and one thing becomes clear: 2026 is one of the most significant structural turning points in the history of online advertising. Ads have started appearing inside ChatGPT, Google has embedded new ad formats into its AI search, and an era in which AI agents buy and sell advertising is becoming the standard.
This piece comes in two parts. First, we'll walk through what changed in 2026 at the market level. Then we'll read those shifts through the lens of an operator who owns their own OTT inventory (with a North American focus) — and unpack the opportunities they create.
Let me give you the conclusion up front. An operator who owns inventory holds two assets no one else can replicate: ① viewing data (first-party data) and ② the screen itself (format control). Neither ad-tech vendors nor agencies hold both at once. And every trend in 2026 is raising the value of exactly these two assets.
Part 1. What Changed in 2026
The market is still growing
Let's start with the big picture. The North American online advertising market is projected to grow from $108.58 billion in 2025 to $216.98 billion by 2033 — a CAGR of 9.04%. As of 2025, North America is the largest region in internet advertising, while Asia-Pacific is the fastest-growing. Global ad spend is expected to surpass $1 trillion for the first time in 2026.
Growth continues — but the real story is that where the money flows and how advertising works are being fundamentally rewired.
The biggest event: ChatGPT now has ads
The most symbolic shift this year is OpenAI bringing advertising to ChatGPT. Because this was a platform that had been ad-free for years, the impact was substantial.
OpenAI began testing ads inside ChatGPT on February 9, 2026, and on May 5 opened a self-serve Ads Manager beta — adding cost-per-click (CPC) bidding, a measurement pixel, and a Conversions API on top of its existing CPM model.
Major agencies including Dentsu, Omnicom, Publicis, and WPP signed on as partners, alongside Adobe, Criteo, Kargo, Pacvue, and StackAdapt. The platform reportedly generated around $100 million in revenue in its first six weeks.
The industry is calling this the most significant shift in digital marketing since Google AdWords. That said, some markets — Canada, for example — have advertiser access that's partner-mediated or still in a waiting state, so rollout speed varies by region.
The essence here isn't simply "AI got ads." It's a shift toward agentic advertising — a structure where AI agents buy and sell ads, or even complete purchases on the consumer's behalf.
New ad formats
The specific new formats that appeared this year make the direction unmistakable.
On the ChatGPT side — three formats launched in March 2026: sponsored answer cards, product spotlight units, and contextual sidebar placements. What's notable is the targeting approach. Rather than demographics or third-party behavioral profiles, it's based on the topic and intent signals of the current conversation.
On the Google side — at Google Marketing Live on May 20, 2026, Google announced four new AI search ad formats: Conversational Discovery ads, Highlighted Answers, AI-powered Shopping ads, and Business Agent for Leads. All are powered by Gemini and currently in testing within AI Mode, and ads inside AI-generated results are clearly labeled as ads. The backdrop: AI Mode has surpassed 1 billion monthly users, with queries doubling every quarter.
Across the board, AI-driven targeting, expanding programmatic adoption, and the spread of immersive formats are leading the way.
Standards are being built: UCP and IAB's Agentic Roadmap
For agents to buy and sell ads, they need a common "language." In 2026, those standards came together quickly.
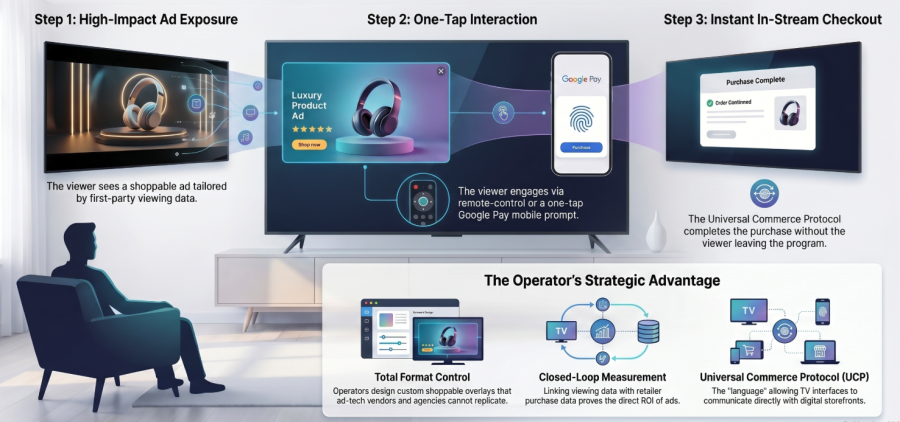
Universal Commerce Protocol (UCP) — announced January 2026. It's a universal language that lets AI agents (such as Google Gemini) communicate directly with your store. An agent can complete the entire purchase journey without the customer ever leaving the chat, and it's rolling out in the US through partners like BigCommerce, Shopify, and Feedonomics.
IAB Tech Lab Agentic Roadmap — announced January 6, 2026. It extends existing standards (OpenRTB, AdCOM, VAST, and others) into an agentic execution layer. Magnite and MiQ already completed one of the first Ad Context Protocol (AdCP) test buys in December 2025, with Scope3 serving as the buyer agent.
New faces: emerging companies and funding
In the gaps opened by this change, new players are emerging fast.
Nectar Social — came out of stealth in May 2026. Led by two former Meta executives, it positions itself as an "agentic operating system for marketing," running more than 10 million autonomous conversations per week and claiming $100 million in attributed revenue across brands like e.l.f. Beauty and Liquid Death.
Plurio — raised $3.5 million in March 2026. It brings agentic AI to performance marketing and manages over $100 million in annual ad spend.
Agentio — raised a $40 million Series B led by Forerunner ($56 million total). It automates brand-creator matching programmatically.
New tools from incumbents — Yahoo DSP's "Yours, Mine, and Ours" framework, Reddit's Max Campaigns (AI media buying), Google's Ask Advisor (a Gemini-powered unified assistant), and Meta Advantage+'s fully automated campaigns (just provide a URL and a budget), among others.
And everything is converging on the TV screen
Separate from AI agents, there's one segment growing faster than any other: the convergence of retail media networks (RMNs) and CTV.
US retail media ad spend is projected to reach $69.33 billion in 2026 — up about $10.53 billion from the prior year. But more than 89% of that increase is expected to be absorbed by Amazon and Walmart. Walmart Connect expanded CTV inventory access in April 2026 (with Vizio supplying premium inventory including Paramount and Warner Bros), and Comcast partnered with Amazon Ads to open up premium Prime Video inventory to local and small-to-medium-sized (SMB) advertisers for the first time.
Which raises the key question: For an OTT operator who owns inventory — not Amazon or Walmart — what room is left?
Part 2. Five Opportunities for OTT Inventory Operators
From here, we re-read the trends above through the lens of an operator who owns their own OTT/streaming inventory (North American market). Listed in order of execution priority.
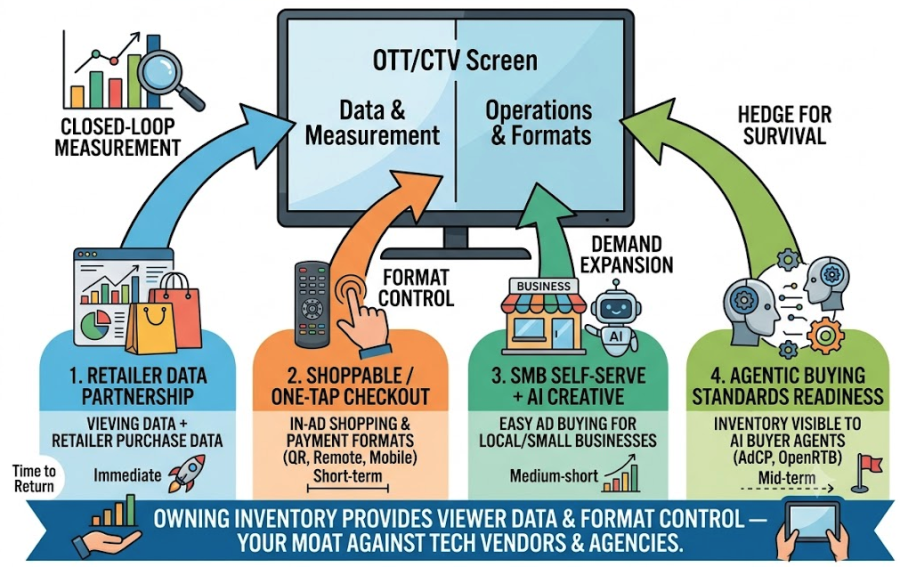
Priority 1 — Wrap your inventory in "closed-loop" measurement via retailer data partnerships
The most powerful short-term lever is to combine your own viewing data with a retailer's purchase data. CTV's long-standing weakness — proving that "people who saw the ad actually bought" — became standard in 2026. The Walmart-Vizio, Walmart-Roku, and Comcast-Amazon Ads partnerships all point in this direction.
Why is this Priority 1? Because the operator already owns the inventory and the viewing data. You only need to fill in the one missing piece — purchase data — through a partnership. Retail media CTV ad spend is growing roughly 3x faster than retail media search, and retail accounts for about one-fifth of CTV spend, the largest share. In other words, demand is already pointed at your screen.
Execution tip: Use clean rooms to form measurement partnerships with mid-market retailers and CPG brands, proving "exposure → shelf" incrementality. CTV premium CPMs currently sit around $25–60, and the more you can prove measurability, the higher up that range you'll command.
Priority 2 — Build shoppable / one-tap checkout formats into your own screen
Owning inventory means you can design the format however you want — precisely the part vendors and agencies can't do. With UCP and in-ad one-tap checkout becoming standard, "see it on TV and buy it instantly" is now technically possible. Walmart-Roku has already enabled remote-control purchases, and Google demonstrated one-tap Google Pay checkout inside an ad.
Execution tip: Build shoppable formats — QR, one-tap, remote-control checkout — directly into your own inventory. They command higher rates than simple impression ads, and combined with Priority 1 (closed-loop measurement) the synergy is significant. The zero-click flow, where the viewer buys without leaving, is the most compelling value proposition for advertisers.
Priority 3 — Self-serve + AI creative for SMB and local advertisers
Premium CTV has traditionally been the domain of large brands. A major axis of new demand in 2026 is opening it up to the local and small-to-medium-sized (SMB) advertisers who couldn't buy in before — Comcast-Amazon opening Prime Video to SMBs being the prime example.
Another CTV bottleneck is video creative production. With 41% of marketers saying it still takes three to four weeks to launch a campaign, AI creative is a clear remedy.
Execution tip: Bundle a self-serve ad manager with AI-generated creative on your own inventory to lower the barrier to entry. Bring the "just enter a URL and a budget and AI builds the CTV video and runs it" flow (Meta Advantage+, TikTok text-to-video) to CTV, and you can absorb untapped long-tail demand. Only an inventory owner can complete this full stack on their own screen.
Priority 4 (a mid-term hedge) — Make your inventory "visible" to agentic buying
Going forward, ad inventory will move toward a structure where AI buyer agents do the buying. The IAB Tech Lab Agentic Roadmap, Magnite embedding a seller agent directly into its SpringServe video ad server, and the MiQ Sigma trading agent are all signals.
INMA's advice to mid-tier publishers lands exactly here — ask your current ad-tech partners when they'll support agentic workflows, and document your inventory's differentiators.
Execution tip: Right now, the standards (AdCP, agentic extensions to OpenRTB, etc.) are just being established, so there's a real first-mover advantage. Conversely, if you're late, you risk your inventory being undiscoverable in the agentic buying era. It's not immediate revenue — it's a hedge for survival two or three years out.
Opportunity Priorities at a Glance
Priority
Opportunity
Asset Leveraged
Time to Return
1
Retailer data partnership → closed-loop measurement
Viewing data + inventory
Immediate (higher rates)
2
Shoppable / one-tap checkout formats
Format control
Short-term
3
SMB self-serve + AI creative
Full-stack inventory
Medium-short (demand expansion)
4
Agentic buying standards readiness
Inventory metadata
Mid-term (defensive)
Closing Thoughts
If you had to sum up North American online advertising in 2026 in one line, it would be this: ads moving inside conversational AI, a market where agents do the buying and selling, and a CTV screen where everything converges.
For an operator who owns their own OTT inventory, the two assets you hold — viewing data and format control — are best leveraged through the Priority 1 and 2 opportunities. Because ad-tech vendors and agencies can't hold both at once, that's exactly where your moat is.
The three things worth doing first:
Pick one of the opportunities above and narrow it down to specific partner candidates, a business model, and a revenue structure
Conduct deep research on North American retailer and measurement (clean room) partner candidates
Design a shoppable format pilot and run pricing simulations
This article is based on news, newswire releases (GLOBE NEWSWIRE, PR Newswire, etc.), and industry analysis published between January and May 2026. Primary sources: ResearchAndMarkets, IAB Tech Lab, AdExchanger, Adweek, TechCrunch, Search Engine Land, Marketing Brew, PPC Land, MediaPost, EMARKETER, Tinuiti, and INMA. Market sizing figures vary by publisher in definition and scope, so caution is warranted in direct comparisons; revenue and spend figures for private startups are based on company disclosures.